
Might be eligible for home financing when you can generate steady income, whether functioning or self-employed. Just like the a self-functioning borrower, showing which you have a professional way to obtain financing will be probably the most vital thinking.
Financial comments and you will tax statements are several common a way to confirm your stable economic avenues. It’s important to make sure that you could potentially show their money with strong files.
Create your earnings records readily available
Extremely mortgage people would like to visit your earnings records for no less than during the last 12 months. Regarding information, loan providers will likely opinion their income tax get back.
Improve your method of ensure you provides an income tax return you to definitely shows an effective net income, especially if you are in the fresh new habit of using much from make-offs.
Financial statements are a different way to show your own monetary supply. Loan providers always require doing 24 months’ worth of financial comments to help you estimate the mediocre month-to-month money. This might be according to dumps made into your finances.
Make a massive down-payment
Lenders generally view you because less of a risk for many who make an enormous down-payment since the in so doing, you’ll encounter reduced debt to settle. Their monthly mortgage repayments might possibly be all the way down, and you can have less currency borrowed for those who standard. Having a downpayment more than 20% may additionally help save you out of having to pay individual home loan insurance.
Not only will a huge down-payment enable it to be easier for that be eligible for home financing, nonetheless it may also make you use of better words such as for instance all the way down rates of interest.
Ready yourself your entire economic documents
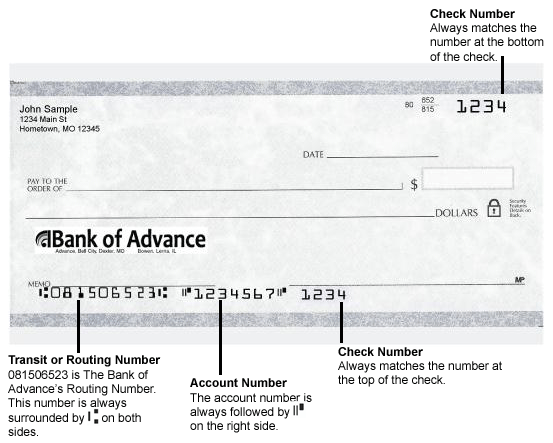
The loan elite group youre working with allow you to see and that economic data you should promote. Whilst it may vary, lender comments and you may tax statements are very requested. Find out if you really have those who work in handy. If you don’t, have them as soon as possible.
Once the mind-employed homeowners tend to have harder sourced elements of income West Virginia title and loan, they should look deeper. Hooking up your accountant together with your lender is one way of doing they otherwise delivering alot more proof earnings.
Make an effort to save
This isn’t a requirement but saving large helps you once you apply for a home loan. In the event the nothing else, it can give you a whole lot more selection such reducing the count out-of debt you are taking towards the by making a huge down-payment.
How do i let you know notice-working earnings to have home financing?
To show self-functioning money having a mortgage, you need to offer a track record of uninterrupted care about-employment income for at least couple of years. Very home loan banking institutions otherwise organizations will appear for the following:
A position verification
A job confirmation will assist you to illustrate that you are thinking-working. One good way to score work confirmation is to try to reveal letters or letters because of these offer:
- current clients
- signed up certified personal accountant
- elite group groups that may be certain that their subscription
- Conducting business Since the (DBA)
- insurance policies to suit your needs
- any business otherwise state permit you hold
Money records
You may be one step nearer to taking approved to possess an excellent financial for those who have earnings documentation. Extremely lenders ask for these data files:
- private tax statements
- profit and loss comments
- bank comments
Would it be best to be applied or worry about-used in a mortgage?
Of a home loan lender’s direction, its more straightforward to dictate your financial condition if you find yourself operating in the place of notice-functioning. We have found an easy article on functioning consumers and you may notice-operating consumers:
Employed mortgage
An applied borrower usually has a developed salary due to their boss and is without difficulty capable of producing a position verification and earnings documents. Loan providers use this guidance to decide just how much earnings the fresh new borrower need to generate to settle its financial.